Funeral home real estate financing plays a critical role in securing a business acquisition loan in the United States. Even a funeral home with consistent call volume, established community relationships, and strong operating cash flow can face financing challenges when its property ownership, lease terms, or real estate valuation creates additional risk for lenders.
When buying a funeral home, one of the most important decisions is whether to purchase the commercial property with the business, lease the building from the seller, or finance the real estate separately. Each option can affect the required down payment, available collateral, monthly expenses, debt service coverage ratio (DSCR), and overall funeral home loan approval.
US lenders evaluate funeral home real estate based on property value, business cash flow, building condition, zoning compliance, lease stability, and the borrower’s ability to repay the proposed debt. An unfavorable lease, low property appraisal, unexpected renovation costs, or unresolved environmental concerns can delay financing even when the operating business is profitable.
Understanding how funeral home commercial real estate loans are structured helps buyers compare SBA 7(a), SBA 504, and conventional financing options while avoiding costly mistakes before signing a purchase agreement.
In this guide: Learn how buying versus leasing funeral home property affects financing, what banks evaluate during underwriting, how real estate appraisals influence loan approval, and which financing structures may fit different funeral home acquisitions.
Why Does Real Estate Matter in Funeral Home Loan Approval?
Funeral home real estate is an important factor in commercial financing because the property is closely connected to daily operations, customer experience, and long-term business stability. Unlike many traditional businesses, funeral homes often require specialized facilities, including preparation rooms, visitation areas, chapels, refrigeration equipment, and dedicated parking.
For funeral home buyers in the United States, the decision to purchase or lease a building can directly influence loan eligibility, collateral requirements, operating expenses, and the amount of financing a lender may approve.
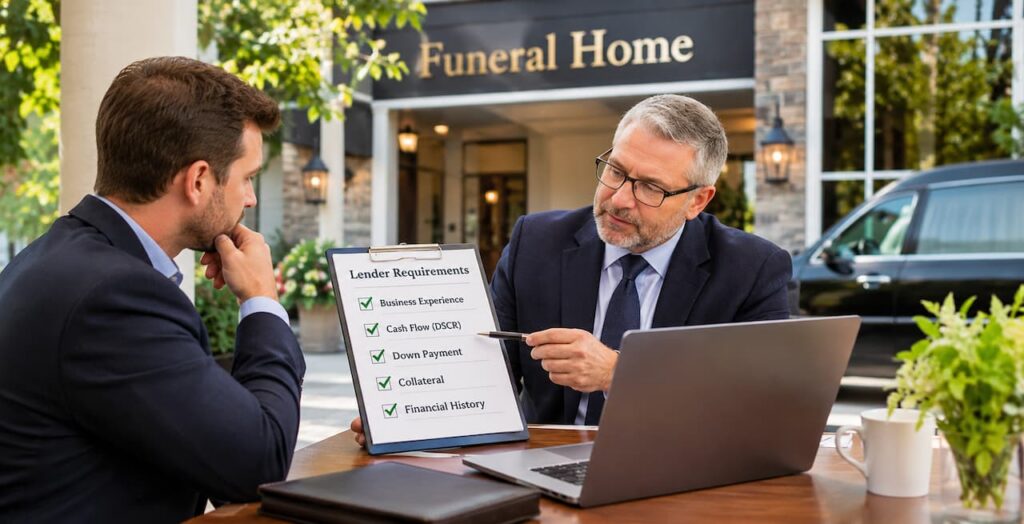
What Banks Evaluate When Financing Funeral Home Real Estate
US lenders typically consider four important factors:
-
Property Collateral: Whether the funeral home building provides sufficient security for the proposed commercial real estate loan.
-
Business Cash Flow: How mortgage payments, rent, property taxes, insurance, and maintenance affect the funeral home’s ability to repay debt.
-
Operational Stability: Whether the buyer has reliable, long-term access to the building and can continue providing funeral services without interruption.
-
Real Estate and Transaction Risk: Whether property valuation, building condition, ownership documents, zoning, or lease agreements create potential financing challenges.
Why Funeral Home Location and Property Control Matter
An established funeral home may have operated in the same community for decades. Its location, accessibility, and relationships with local families can contribute to ongoing business performance.
Relocating a funeral home may require significant investment in property improvements, equipment, licensing, and marketing. These expenses can affect available working capital and future cash flow.
However, owning the funeral home building is not always necessary for loan approval. A well-structured, affordable, long-term lease may also support financing when it satisfies the lender’s requirements.
The key is demonstrating that the proposed real estate arrangement supports business continuity, predictable operating expenses, and sustainable debt repayment.
Before choosing to buy or lease funeral home property, buyers should evaluate both the financial obligations and the long-term operational risks associated with each option.
Buying vs. Leasing Funeral Home Real Estate: Which Is Better for Financing?
When purchasing an existing funeral home in the United States, buyers must decide whether to acquire the commercial property along with the operating business or lease the facility from the seller or another property owner.
Both options can support funeral home acquisition financing, but they affect the total purchase cost, down payment requirements, business cash flow, collateral, and long-term financial stability differently.
Option 1: Buying the Funeral Home and Real Estate Together
Purchasing both the funeral home business and its property provides greater control over the facility and may strengthen the transaction by adding tangible real estate collateral.
Potential advantages include:
-
Long-Term Property Control: Ownership reduces the risk of lease expiration, landlord disputes, or unexpected changes to rental terms.
-
Real Estate Collateral: The building may provide additional security for a commercial funeral home loan.
-
Property Equity: Buyers may build real estate equity over time, depending on market conditions and outstanding debt.
-
Operational Flexibility: Property ownership can provide more control over renovations, equipment installation, and long-term facility improvements.
However, purchasing the building also increases the total acquisition cost. Buyers may need additional equity, an acceptable property appraisal, inspections, environmental documentation, and financing sufficient to support both the operating business and real estate.
Property ownership also involves ongoing expenses, including taxes, insurance, maintenance, and major capital improvements.
Option 2: Buying the Funeral Home Business and Leasing the Property
In some funeral home acquisitions, the seller retains ownership of the building while transferring the operating business to the buyer.
Leasing may reduce the initial purchase price and allow buyers to preserve capital for working expenses, staffing, and operational improvements.
However, the lease becomes an important part of the lender’s underwriting review.
Banks typically evaluate:
-
Lease Duration: Whether the agreement provides sufficient occupancy security for the proposed financing.
-
Renewal Options: Whether the buyer can extend the lease under clearly defined terms.
-
Rent and Annual Increases: Whether rental payments are affordable and supported by funeral home cash flow.
-
Lease Assignment: Whether the lease can transfer to the new business owner.
-
Maintenance Responsibilities: Which party must pay for repairs, insurance, taxes, and property improvements.
-
Lender Protections: Whether the landlord will provide any required notices, access rights, or other lender agreements.
A lease with unfavorable renewal terms, excessive rent increases, or restrictions on ownership transfers may create financing problems even when the funeral home has strong historical revenue.
How Do Banks Compare Buying vs. Leasing a Funeral Home?
When evaluating funeral home real estate financing, US lenders compare the financial implications of both structures.
Buying the property may provide additional collateral and long-term operating stability, but it can increase the loan amount and required buyer equity.
Leasing may reduce the initial capital investment, but ongoing rent becomes an operating expense that affects available cash flow and debt service coverage.
Neither option automatically guarantees better loan terms or approval.
The most suitable structure depends on property value, business profitability, available capital, lease conditions, expected operating expenses, and the funeral home’s long-term ownership goals.
Before signing a funeral home purchase agreement, buyers should review the property arrangement with their lender and a qualified commercial real estate attorney to identify potential financing or legal concerns.
How Funeral Home Property Ownership Affects Loan Approval
Funeral home property ownership can significantly influence commercial loan approval in the United States. When evaluating a funeral home acquisition, banks consider whether the buyer will own the building, lease the property, or use a separate real estate ownership structure.
Although owning commercial real estate may provide additional collateral and long-term operational stability, property ownership alone does not guarantee funeral home loan approval. Lenders must also evaluate business cash flow, property value, operating expenses, and the borrower’s financial qualifications.
What Banks Look for When Real Estate Is Included
US lenders typically review several important factors before approving financing for a funeral home that includes commercial property.
-
Property Appraisal and Market Value: Banks evaluate whether an independent appraisal supports the property’s proposed purchase price and its value as collateral.
-
Building Condition: Lenders consider necessary repairs, deferred maintenance, equipment upgrades, and potential renovation expenses that could affect the buyer’s available capital.
-
Ownership and Title Documentation: The lender reviews property ownership, existing liens, title concerns, and the seller’s ability to transfer the real estate.
-
Business Cash Flow and DSCR: The funeral home’s historical earnings must support the proposed loan payments, including relevant property expenses.
-
Zoning and Permitted Use: Banks may need confirmation that the property can legally continue operating as a funeral home after the acquisition.
-
Environmental Considerations: Depending on the property and financing program, lenders may require environmental assessments or additional investigations.
Can a Leased Funeral Home Qualify for Acquisition Financing?
Yes. Buying a funeral home business without purchasing the building may still qualify for acquisition financing.
However, lenders evaluate whether the lease provides sufficient operational stability, reasonable rental expenses, and appropriate protections throughout the financing period.
A business operating under a secure, affordable long-term lease may present less risk than a property acquisition involving an inflated purchase price, significant repairs, or insufficient cash flow.
The lender must understand how rental payments, lease renewal options, and property control affect the funeral home’s ability to operate and repay its debt.
How Property Ownership Influences the Loan Structure
When a funeral home acquisition includes real estate, equipment, and business goodwill, lenders evaluate how the total purchase price is allocated among those assets.
The amount supported by commercial property collateral may differ from the amount needed to purchase the operating business.
This distinction can affect the financing program, required buyer equity, property appraisal, repayment terms, and overall transaction structure.
Buyers evaluating a combined business and property purchase should understand how funeral home acquisition loans are structured before finalizing the purchase agreement.
Ultimately, the strongest property arrangement is one that supports sustainable cash flow, provides operational stability, and satisfies the lender’s underwriting requirements.
her.
How Funeral Home Property Appraisals Affect Loan Approval
A funeral home property appraisal plays an important role in commercial real estate financing because lenders need to determine whether the building’s value supports the proposed loan.
When buying a funeral home in the United States, the seller’s asking price does not necessarily represent the property’s appraised market value. Banks may require an independent commercial real estate appraisal to evaluate collateral, financing risk, and the amount they are willing to lend.
Funeral home properties can be more challenging to value than traditional commercial buildings because they often contain specialized facilities, preparation rooms, visitation areas, chapels, and equipment designed for funeral service operations.
The building’s location, condition, zoning, comparable property sales, and potential alternative uses can influence its market value.
What Happens When a Funeral Home Property Appraisal Comes in Low?
A low commercial property appraisal can create financing challenges when the appraised value is below the portion of the purchase price allocated to real estate.
Consider this illustrative funeral home acquisition:
| Financial Factor | Amount |
|---|---|
| Seller’s proposed property price | $1,200,000 |
| Appraised property value | $950,000 |
| Difference | $250,000 |
In this example, the funeral home property appraises for $250,000 less than the seller’s proposed price.
This does not automatically mean the bank will reject the funeral home acquisition loan. However, the lender may reconsider the amount supported by the property, the buyer’s equity contribution, or the overall financing structure.
Depending on the transaction, the buyer may need to negotiate a lower purchase price, contribute additional capital, provide further valuation evidence, or explore another eligible financing arrangement.
Why Funeral Home Property Valuation Matters to Lenders
US lenders evaluate a funeral home’s real estate value alongside the operating business’s financial performance.
An established funeral home may generate reliable earnings and have valuable business goodwill, but those factors do not automatically increase the independently appraised value of the building.
Banks typically distinguish between:
-
Commercial Real Estate Value: The market value of the property and qualifying building improvements.
-
Business Goodwill: The operating business’s reputation, customer relationships, and other intangible value.
-
Equipment and Business Assets: Vehicles, preparation equipment, furniture, and other assets included in the acquisition.
Separating these components helps lenders determine how the purchase price and loan amount should be evaluated.
How to Avoid Funeral Home Appraisal Problems
Before finalizing a funeral home property purchase, buyers should:
-
Review the Purchase Price Allocation: Identify how much of the total acquisition price relates to real estate, business goodwill, and equipment.
-
Evaluate Property Condition: Consider necessary repairs, building improvements, and any issues that may affect marketability or property value.
-
Discuss Appraisal Requirements Early: Ask the lender what valuation documentation is required and how an appraisal shortfall could affect financing.
Buyers should avoid assuming that a seller’s valuation will automatically satisfy commercial lending requirements.
An early property valuation discussion can help identify financing gaps, reduce underwriting surprises, and improve financial planning before closing.
Ultimately, a funeral home property appraisal helps lenders assess whether the proposed real estate financing is supported by the collateral and whether the overall acquisition is financially sustainable.
How Funeral Home Rent Affects Cash Flow and Loan Approval
Rental expenses play an important role in funeral home financing because they directly affect operating cash flow and the business’s ability to repay its acquisition loan.
When purchasing a funeral home in the United States without buying the building, the buyer may need to lease the property from the seller or another commercial landlord. Although leasing can reduce the initial acquisition cost, monthly rent becomes an ongoing operating expense that lenders must consider during underwriting.
This is especially important when the previous owner also owned the property and charged the funeral home little or no rent. After the acquisition, the new owner may face significantly higher property expenses, reducing the cash flow available for debt payments.
How Higher Rent Changes Funeral Home DSCR
The debt service coverage ratio (DSCR) measures whether a funeral home’s available cash flow can support its annual loan payments.
Consider this illustrative example:
| Financial Measure | Scenario A | Scenario B |
|---|---|---|
| Annual cash flow before rent | $300,000 | $300,000 |
| Annual facility rent | $60,000 | $120,000 |
| Cash flow available for debt service | $240,000 | $180,000 |
| Annual debt payments | $160,000 | $160,000 |
| Illustrative DSCR | 1.50x | 1.13x |
In this example, increasing annual rent by $60,000 reduces the funeral home’s DSCR from 1.50x to approximately 1.13x.
This difference can significantly affect loan approval because lenders need confidence that the business can consistently meet its debt obligations after accounting for realistic operating expenses.
The example is simplified. Actual underwriting calculations may also consider owner compensation, normalized earnings, existing obligations, and other financial adjustments.
For a detailed explanation of the calculation, read our guide to DSCR for funeral home loans.
What Banks Review in Funeral Home Lease Expenses
When evaluating a funeral home acquisition involving leased real estate, US lenders typically examine:
-
Monthly and Annual Rent: Whether the proposed rental expense is affordable based on historical and projected business cash flow.
-
Rent Escalation Clauses: Whether annual increases could weaken profitability or repayment capacity.
-
Property Taxes and Insurance: Whether the tenant must cover additional ownership-related expenses under the lease.
-
Maintenance and Repair Responsibilities: Whether the funeral home must pay for expensive building repairs or equipment replacements.
-
Lease Duration and Renewal Terms: Whether the business has sufficient occupancy security to support the proposed financing.
A lease with affordable base rent may still create financial pressure if the tenant must cover substantial maintenance expenses, insurance, property taxes, or unexpected repairs.
How to Avoid Rent-Related Funeral Home Financing Problems
Before signing a funeral home lease or acquisition agreement, buyers should compare the proposed rental payments with local commercial property conditions and the business’s historical financial performance.
Buyers should also prepare a realistic post-acquisition operating budget that includes rent, employee salaries, utilities, insurance, property maintenance, and loan payments.
If the proposed rent significantly reduces DSCR, the buyer may need to negotiate different lease terms, reconsider the purchase price, increase available equity, or explore another suitable financing structure.
The goal is to ensure the funeral home can afford both its property expenses and loan payments without placing unnecessary pressure on working capital.
Ultimately, rental costs should be evaluated before finalizing the acquisition because even a profitable funeral home may struggle to qualify for financing when its lease obligations reduce available cash flow.
How Short Funeral Home Lease Terms Can Affect Loan Approval
When buying a funeral home in the United States without purchasing the building, the commercial lease becomes an important part of the acquisition financing process. Even if the business has consistent revenue and strong cash flow, an unfavorable or short-term lease can create concerns for lenders.
A funeral home depends on its physical location to provide services, maintain community relationships, and operate specialized facilities. If the lease expires before the business has sufficient time to repay its acquisition loan, the lender may question whether operations can continue without interruption.
A short lease does not automatically prevent financing, but lenders generally want reasonable assurance that the funeral home will have reliable access to its property throughout the relevant financing period.
What Lease Terms Do Banks Review for Funeral Home Loans?
When evaluating a funeral home acquisition involving leased commercial real estate, US lenders commonly review the following provisions:
-
Lease Duration: Whether the remaining lease term provides sufficient operational stability for the proposed financing.
-
Renewal Options: Whether the buyer has enforceable options to extend occupancy under clearly defined conditions.
-
Rent Increases: Whether future rental adjustments are predictable and affordable based on the funeral home’s projected cash flow.
-
Lease Assignment: Whether the existing lease can transfer to the new business owner without creating legal or operational complications.
-
Default and Termination Provisions: Circumstances that allow the landlord to terminate the lease and how these provisions could affect business continuity.
-
Purchase Options: Whether the buyer has the contractual right to purchase the property later and under what conditions.
-
Lender Protections: Whether the landlord will provide any necessary notices, access rights, or other agreements requested by the financing institution.
The specific requirements depend on the lender, loan structure, and applicable financing program.
Why Lease Renewal Rights Matter When Buying a Funeral Home
A funeral home may have operated at the same location for decades, but that history does not guarantee the new owner will have the right to remain there.
For example, purchasing an established funeral home with only two years remaining on its lease could create financing challenges if the buyer has no reliable renewal rights.
The lender may require additional information or changes to the lease before proceeding with the loan.
Buyers should confirm that renewal options, rent adjustments, and assignment rights are documented rather than relying on informal assurances from the seller or landlord.
How to Avoid Lease-Related Funeral Home Financing Delays
Before signing a funeral home purchase agreement, buyers should review the proposed lease with their lender and a qualified commercial real estate attorney.
Important steps include confirming the remaining lease term, reviewing renewal and termination provisions, estimating future rental expenses, and identifying any lender-required agreements.
If the lease presents significant risks, negotiating longer occupancy rights or clearer renewal provisions before closing may improve the transaction’s financing prospects.
The objective is to protect the funeral home’s long-term operating location while ensuring that lease obligations remain affordable and consistent with the business’s repayment capacity.
A well-structured commercial lease can help support funeral home acquisition financing, even when the buyer does not own the property.
How Funeral Home Building Condition Affects Loan Approval
The condition of a funeral home building can significantly affect commercial real estate financing and loan approval in the United States. Even when a funeral home has consistent revenue, strong community relationships, and sufficient cash flow, unexpected property repairs or equipment problems can create challenges during lender underwriting.
Funeral homes often operate in specialized buildings with preparation rooms, chapels, visitation areas, refrigeration equipment, and other facilities essential to daily operations. These features may require substantial maintenance or upgrades, particularly when purchasing an older funeral home property.
US lenders evaluate building condition to determine whether the property supports the proposed financing and whether the buyer has sufficient capital to address necessary improvements after closing.
What Property Conditions Do Banks Review?
When financing a funeral home acquisition that includes commercial real estate, lenders may examine:
-
Roof and Structural Condition: Roofing problems, foundation concerns, and structural repairs that could affect property value or safety.
-
Electrical, Plumbing, and HVAC Systems: Outdated systems that may require immediate repairs or replacement.
-
Accessibility and Building Compliance: Potential improvements needed to satisfy applicable accessibility, building, and safety requirements.
-
Preparation Rooms and Refrigeration Equipment: The condition of specialized facilities and equipment used in funeral home operations.
-
Crematory Equipment and Permits: Equipment condition, installation requirements, and applicable permits when an on-site crematory is included.
-
Parking and Property Access: Adequate parking, entrances, accessibility, and site conditions.
-
Deferred Maintenance: Repairs or capital improvements that the previous owner postponed.
The lender’s specific inspection and documentation requirements depend on the property’s condition, transaction structure, and financing program.
Example: How Unexpected Repairs Can Affect Funeral Home Financing
Consider a funeral home buyer who has arranged financing and reserved enough capital for the down payment, closing expenses, and initial operations.
During property due diligence, a professional inspection identifies $150,000 in necessary building repairs and improvements.
This discovery may affect the acquisition in several ways:
-
The lender may reassess the total project cost and required buyer equity.
-
The buyer may need additional working capital or a revised repair budget.
-
The purchase price or financing structure may need to be renegotiated.
-
Closing could be delayed until necessary inspections, estimates, or repairs are addressed.
If essential repairs are required for lawful operation, the transaction may not be able to close under its original terms.
This example illustrates why funeral home buyers should evaluate property condition before committing most of their available funds to the acquisition.
How to Avoid Building-Related Loan Delays
Before purchasing a funeral home with commercial real estate, buyers should arrange appropriate professional property inspections and request realistic estimates for necessary repairs.
A building condition review should identify immediate maintenance requirements, equipment replacement needs, and potential improvements that could affect business operations.
Buyers should also discuss significant repair costs with their lender early in the financing process. Depending on the loan program and eligibility requirements, certain property improvements may be included in the financing structure.
The goal is to ensure that the funeral home can cover its property expenses, necessary improvements, operating costs, and loan payments without creating excessive financial pressure.
Addressing building condition concerns before final underwriting can reduce unexpected costs, protect available working capital, and improve the buyer’s preparation for closing.
How Environmental and Zoning Issues Affect Funeral Home Real Estate Financing
Environmental and zoning requirements can significantly affect funeral home real estate financing in the United States. Even when a funeral home has strong cash flow and an acceptable property appraisal, unresolved environmental concerns or property-use restrictions may delay loan approval and closing.
Funeral home properties may contain specialized preparation facilities, embalming areas, chemical storage, refrigeration equipment, or on-site crematories. Depending on the property’s history and intended use, these features may require additional investigation during commercial real estate due diligence.
US lenders evaluate environmental and zoning risks to determine whether the property can continue operating legally and whether potential liabilities could affect its value, collateral suitability, or the borrower’s repayment capacity.
What Environmental Assessments Do Funeral Home Lenders Require?
Depending on the financing program, property characteristics, and lender requirements, a bank may request a Phase I Environmental Site Assessment (ESA) before approving a funeral home commercial real estate loan.
A Phase I ESA generally involves reviewing historical property uses, available environmental records, and site conditions to identify potential environmental concerns.
Issues that may require further investigation include:
-
Historical Chemical Storage: Past storage or handling of embalming chemicals and other potentially hazardous materials.
-
Underground Storage Tanks: Existing or former tanks that may present contamination concerns.
-
Previous Property Uses: Historical commercial or industrial activities that could have affected soil or groundwater.
-
Crematory Operations: Applicable environmental permits, equipment-related requirements, and potential compliance concerns.
-
Suspected Contamination: Conditions that may require additional environmental investigation or remediation.
A Phase I assessment does not automatically mean the property is contaminated. Its purpose is to identify potential environmental risks.
If significant concerns are discovered, the lender may request further investigation before proceeding with financing.
Why Zoning and Permitted Property Use Matter
Zoning regulations determine whether a property can legally operate as a funeral home and whether certain funeral-related activities are permitted at that location.
Although an existing funeral home may have operated from the same building for many years, buyers should not assume that every approval automatically transfers after a change in ownership.
Before purchasing funeral home real estate, buyers should investigate:
-
Permitted Funeral Home Use: Whether current zoning allows continued funeral service operations.
-
Special-Use Permits: Whether existing approvals remain valid or require updates.
-
Ownership Transfer Requirements: Whether a new owner must obtain additional permits, registrations, or approvals.
-
Crematory Regulations: Whether on-site cremation activities require separate zoning or environmental approvals.
-
Planned Renovations or Expansion: Whether proposed building modifications are allowed.
-
Nonconforming Property Uses: Whether the funeral home operates under existing-use protections that could limit future changes.
Requirements vary by state, county, and municipality. Buyers should verify the applicable rules with local authorities and qualified professionals.
How Environmental or Zoning Problems Can Delay Loan Approval
Environmental concerns or unresolved zoning issues can create additional financial and operational risks during funeral home acquisition financing.
For example, if an environmental assessment identifies a potential contamination issue, the lender may require additional reports, corrective action, or evidence that the issue has been adequately addressed.
Similarly, if zoning restrictions prevent the buyer from continuing a planned funeral home operation or expanding the facility, the bank may need to reassess the proposed transaction.
Depending on the circumstances, these findings may affect property valuation, collateral acceptance, financing terms, or the closing timeline.
How to Avoid Environmental and Zoning Financing Problems
Before signing a binding funeral home property purchase agreement, buyers should discuss environmental due diligence and zoning requirements with their lender.
Important preparation steps include:
-
Reviewing available property records, historical uses, and environmental documentation.
-
Confirming permitted funeral home operations and any necessary local approvals.
-
Identifying environmental assessment requirements early in the financing process.
When potential concerns arise, buyers should consult qualified environmental professionals, local permitting authorities, and a commercial real estate attorney.
The goal is to confirm that the property can legally and safely support funeral home operations without creating unexpected financial obligations after closing.
Addressing environmental and zoning issues early can reduce underwriting delays, protect the buyer’s investment, and support a more reliable funeral home real estate financing process.
Best Financing Options for Funeral Home Commercial Real Estate
Choosing the right funeral home real estate financing structure depends on the property value, total acquisition cost, business cash flow, available buyer equity, and the assets included in the transaction.
In the United States, funeral home buyers typically consider three financing options: SBA 7(a) loans, SBA 504 loans, and conventional commercial real estate loans.
Each option has different eligibility requirements, financing purposes, collateral expectations, and repayment terms.
1. SBA 7(a) Loans for Funeral Home Real Estate and Acquisitions
SBA 7(a) financing may be suitable for eligible funeral home acquisitions that include both the operating business and commercial real estate.
A key advantage is that qualifying SBA 7(a) loans can finance multiple acquisition costs within an approved transaction, including:
-
Funeral home commercial property and qualifying improvements.
-
Business goodwill, equipment, and other eligible acquisition assets.
-
Working capital needed for eligible business operations.
The standard SBA 7(a) program offers loans of up to $5 million. Loan repayment terms depend on the approved use of funds, with qualifying real estate financing potentially supporting terms of up to 25 years.
Lenders also evaluate the funeral home’s historical cash flow, buyer qualifications, available equity, business valuation, and ability to repay the proposed loan.
SBA 7(a) can be worth considering when the transaction includes substantial business goodwill alongside the property.
2. SBA 504 Loans for Funeral Home Property Purchases
The SBA 504 program is primarily designed to support eligible long-term fixed-asset investments, including owner-occupied commercial real estate, construction, building improvements, and qualifying major equipment.
This financing option may be particularly relevant when an existing funeral home owner wants to purchase the building currently being leased or expand an established facility.
SBA 504 financing typically involves a participating commercial lender and a Certified Development Company (CDC), with the borrower contributing the required equity.
Potential advantages include long-term repayment options and fixed interest rates on the CDC-financed portion.
However, SBA 504 loans cannot finance funeral home goodwill or ordinary working capital. Buyers must also satisfy applicable owner-occupancy, eligibility, and project requirements.
For a detailed comparison, read our SBA 7(a) vs. SBA 504 funeral home financing guide.
3. Conventional Commercial Real Estate Loans for Funeral Homes
Conventional funeral home commercial real estate financing is provided by banks or commercial lenders without an SBA government guarantee.
This option may be suitable for established funeral home owners or qualified buyers with strong operating histories, reliable business cash flow, sufficient equity, and acceptable collateral.
Conventional lenders typically review:
-
Property Appraisal: Whether the real estate provides adequate collateral support.
-
Debt Service Coverage: Whether business earnings can cover proposed mortgage and other loan payments.
-
Borrower Financial Strength: Available capital, credit history, industry experience, and existing financial obligations.
-
Loan Structure: Interest rates, repayment periods, collateral requirements, and any refinancing or maturity provisions.
Conventional financing may provide flexibility for certain transactions, but down payment requirements and loan terms vary by lender.
How to Choose the Right Funeral Home Real Estate Loan
The most suitable financing option depends on what the buyer is purchasing and how the transaction is structured.
SBA 7(a) may be appropriate when acquiring an operating funeral home together with real estate, goodwill, equipment, and eligible working capital needs.
SBA 504 may be worth evaluating when the primary goal is purchasing, constructing, or improving eligible owner-occupied commercial property.
Conventional financing may be suitable when the borrower has strong financial qualifications and the transaction meets a bank’s collateral and underwriting requirements.
Before selecting a financing program, funeral home buyers should compare total borrowing costs, required equity, repayment terms, eligible expenses, and projected cash flow after closing.
The best funeral home real estate financing structure is one that supports the business’s long-term operations while maintaining sufficient working capital and sustainable debt repayments.
Should You Hold Funeral Home Real Estate in a Separate LLC?
When purchasing a funeral home in the United States, some buyers consider holding the commercial real estate in a separate limited liability company (LLC) rather than placing both the property and operating business under one entity.
Under this arrangement, one entity owns the funeral home building, while another operates the business and pays rent to the property-owning company.
This structure may support certain ownership, liability management, tax planning, and long-term real estate investment objectives. However, a separate LLC does not automatically improve funeral home loan eligibility or financing terms.
How a Separate Real Estate LLC Works
A funeral home buyer may establish two entities:
-
Property-Holding LLC: Owns the commercial real estate and receives rental payments.
-
Operating Company: Manages funeral services, employees, equipment, customer relationships, and daily business operations.
The two entities typically enter into a formal lease agreement defining rent, maintenance responsibilities, insurance obligations, and occupancy rights.
For financing purposes, lenders evaluate whether the proposed arrangement provides adequate collateral, predictable operating expenses, and sufficient cash flow to support the loan.
How Banks Evaluate Separate Funeral Home Ownership Entities
When a funeral home operates from property owned by a related LLC, US lenders may review several factors:
-
Ownership Structure: Who owns each entity and how the ownership interests are related.
-
Intercompany Lease: Whether rental payments and lease terms are properly documented and financially reasonable.
-
Debt Service Coverage: Whether the operating business can afford rent while meeting its other loan obligations.
-
Collateral and Guarantees: Whether the lender requires property liens, personal guarantees, or additional security arrangements.
-
Legal and Tax Documentation: Whether the proposed structure complies with applicable laws and financing requirements.
-
Loan Program Eligibility: Whether the ownership and occupancy arrangements satisfy the requirements of the selected financing program.
For SBA-backed funeral home financing, eligible property ownership and occupancy arrangements must satisfy the applicable SBA rules. Buyers should confirm the proposed entity structure with their lender before forming or transferring ownership interests.
Potential Advantages and Risks of a Separate Property LLC
Potential advantages may include clearer separation of property ownership and operating activities, flexibility in long-term ownership planning, and the ability to evaluate property-related finances independently.
However, the structure can also introduce additional accounting expenses, legal documentation, tax considerations, and financing complexity.
Lenders may require guarantees or collateral arrangements involving both entities. As a result, creating separate companies does not necessarily eliminate financial exposure between the real estate and operating business.
A poorly structured intercompany lease can also reduce the funeral home’s reported operating cash flow or create problems during underwriting.
Should Funeral Home Buyers Use a Separate LLC?
A separate property LLC may make sense for certain funeral home acquisitions, especially when the buyer has long-term real estate ownership or investment objectives.
However, the decision should depend on the complete transaction structure, property value, business cash flow, financing program, and legal and tax considerations.
Before establishing separate ownership entities, buyers should consult their commercial lender, qualified attorney, and accountant.
The goal is to create an ownership structure that supports business operations, meets financing requirements, and remains practical over the long term—not simply to add another LLC.
Can You Buy a Funeral Home Business Now and the Real Estate Later?
Yes, buying a funeral home business without immediately purchasing the commercial real estate is possible in the United States. In some acquisitions, the buyer purchases the operating business while leasing the building from the seller or another property owner, with plans to acquire the real estate later.
This arrangement may reduce the initial acquisition cost and allow the buyer to preserve working capital for payroll, equipment, operational improvements, and existing business expenses.
However, future funeral home real estate financing is not guaranteed. Buyers must carefully evaluate the lease agreement, property purchase rights, financing eligibility, and long-term affordability before committing to this strategy.
How Buying the Business First Can Work
A funeral home buyer may initially finance the purchase of the operating business, including eligible equipment, goodwill, and other acquisition assets.
The buyer then leases the facility under an agreement that provides continued access to the property while the business operates.
Depending on the agreement, the buyer may negotiate an option to purchase the property at a later date.
This structure can be useful when the buyer wants to establish ownership of the funeral home business before taking on additional commercial real estate debt.
However, lenders still evaluate rental expenses, lease stability, available equity, and the business’s ability to repay the initial acquisition loan.
Important Lease and Future Purchase Terms to Review
Before purchasing a funeral home business with plans to acquire the building later, buyers should review several contractual provisions:
-
Option to Purchase: Whether the agreement gives the buyer a contractual right to purchase the property under defined conditions.
-
Right of First Refusal: Whether the buyer has the opportunity to match certain third-party purchase offers, if applicable.
-
Property Valuation: Whether the future purchase price is established or determined using an agreed valuation method.
-
Lease Duration: Whether the lease provides sufficient time to arrange future financing.
-
Renewal Rights: Whether the buyer can continue operating if the property purchase is delayed.
-
Financing Contingencies: Whether the contract addresses circumstances where future loan approval is unavailable.
An option to purchase and a right of first refusal are not the same. Buyers should have a qualified commercial real estate attorney review the specific contractual rights before signing.
How Banks Evaluate a Future Funeral Home Property Purchase
When the funeral home owner later applies for commercial real estate financing, the lender will evaluate the transaction based on the financial conditions and lending requirements in effect at that time.
Important considerations may include:
-
Business Cash Flow: Whether the funeral home generates sufficient earnings to support existing debt and the proposed property loan.
-
Property Appraisal: Whether the current real estate value supports the requested financing.
-
Available Equity: Whether the borrower has sufficient capital for the proposed purchase.
-
Existing Financial Obligations: Whether the business can manage both operating expenses and additional debt payments.
-
Property Condition: Whether necessary repairs, inspections, and other due diligence requirements have been addressed.
Financing options may include an eligible SBA real estate loan or conventional commercial mortgage, depending on borrower qualifications, transaction structure, and applicable program requirements.
Is Buying the Funeral Home Property Later a Good Strategy?
Purchasing the operating business first may be a practical option when the buyer wants to reduce the immediate capital commitment or when the seller prefers to retain property ownership temporarily.
However, the strategy also creates risks. Property values, interest rates, lending policies, and business performance may change before the future purchase.
Buyers should not assume that the property will automatically qualify for financing simply because they already own the funeral home business.
The best approach is to negotiate secure occupancy rights, understand future purchase conditions, and evaluate whether the business can realistically support additional real estate debt.
Careful planning can help funeral home owners maintain operational stability while preserving the option to purchase their commercial property when financially appropriate.
How Funeral Home Real Estate Decisions Affect Refinancing Options
Funeral home real estate refinancing allows eligible business owners in the United States to replace or restructure existing commercial property debt. Depending on the transaction, refinancing may help improve monthly cash flow, adjust repayment terms, consolidate eligible debt, or support future business expansion.
However, owning valuable funeral home real estate does not automatically guarantee refinancing approval. Banks evaluate the property’s current market value, outstanding mortgage balance, business profitability, existing loan obligations, and the borrower’s overall financial position.
For funeral home owners considering refinancing, the original property ownership structure can influence which financing options are available and how lenders evaluate the transaction.
What Banks Review When Refinancing Funeral Home Real Estate
US commercial lenders commonly evaluate several factors before approving a funeral home real estate refinance:
-
Current Property Value: Whether an updated commercial appraisal supports the requested refinancing amount.
-
Outstanding Mortgage Balance: How much debt remains secured by the funeral home property.
-
Business Cash Flow and DSCR: Whether the funeral home’s operating earnings can support the proposed loan payments.
-
Existing Liens and Collateral: Whether other loans, property liens, or security arrangements affect the refinancing.
-
Loan Maturity and Prepayment Terms: Whether the existing mortgage has an upcoming balloon payment, prepayment penalty, or other contractual obligation.
-
Purpose of Refinancing: Whether the owner intends to restructure existing debt, improve cash flow, or finance an eligible business investment.
-
Ownership Structure: Whether the property belongs to the operating business, a separate LLC, or another related entity.
Lenders also consider the borrower’s credit profile, available liquidity, and applicable financing program requirements.
Can Refinancing Reduce Funeral Home Loan Payments?
Refinancing may reduce monthly loan payments when the new financing structure provides a lower interest rate, an extended repayment period, or other favorable terms.
For example, a funeral home owner with an existing commercial mortgage may explore refinancing to replace a loan approaching maturity or to improve monthly debt obligations.
However, lower monthly payments do not necessarily mean lower total borrowing costs.
Extending the repayment period may increase total interest paid. Refinancing can also involve appraisal fees, lender charges, closing expenses, and applicable prepayment penalties.
Before refinancing, funeral home owners should compare the proposed loan’s total cost with their existing financing obligations.
How Property Equity Affects Funeral Home Refinancing
Property equity is the difference between the funeral home’s current market value and the outstanding debt secured by the property.
Although higher equity may strengthen a refinancing application, banks do not automatically allow owners to borrow against all available property value.
The financing amount depends on factors such as collateral requirements, loan-to-value limits, business cash flow, existing obligations, and the intended use of funds.
For funeral homes with separate property-holding LLCs, lenders may also evaluate intercompany leases, related-party ownership, and applicable guarantees.
When Should Funeral Home Owners Consider Refinancing?
Funeral home owners may consider commercial real estate refinancing when:
-
An existing property loan is approaching maturity or has a balloon payment.
-
Current financing terms place unnecessary pressure on operating cash flow.
-
The business wants to restructure eligible debt or evaluate expansion financing.
-
Changes in property value, business performance, or financial qualifications create an opportunity to review alternative loan structures.
Before pursuing refinancing, owners should review their existing mortgage documents, estimate the property’s current value, prepare updated financial statements, and evaluate potential refinancing costs.
The best funeral home refinancing structure is one that supports manageable debt payments, preserves sufficient working capital, and aligns with the business’s long-term financial goals.
Careful financial planning and early discussions with a qualified commercial lender can help funeral home owners determine whether refinancing is appropriate for their situation.
6 Funeral Home Real Estate Mistakes That Can Delay Loan Approval
When purchasing a funeral home in the United States, real estate decisions can create financing challenges even when the business has strong revenue and consistent cash flow. Property valuation, commercial lease terms, building condition, and ownership arrangements all influence how lenders evaluate a funeral home acquisition.
Avoiding common funeral home real estate financing mistakes can help buyers prepare a stronger loan application, reduce unexpected expenses, and prevent unnecessary delays during underwriting.
1. Agreeing to a Funeral Home Property Price Without Reviewing Appraisal Risk
A common mistake is assuming that the lender will finance the seller’s requested property price without an independent valuation.
Commercial lenders generally evaluate the property’s market value and collateral suitability. If the appraisal comes in below the proposed purchase price, the buyer may need additional equity or a revised financing structure.
Better Approach: Discuss the proposed real estate price with your lender early. Review the purchase price allocation between the building, equipment, and business goodwill, and understand how an appraisal shortfall could affect financing.
2. Signing a Commercial Lease Without Long-Term Protection
Buying a funeral home business while leasing its building can reduce the initial capital investment. However, a short lease or unfavorable agreement may threaten the business’s long-term operating stability.
Lenders may be concerned about limited renewal rights, unpredictable rent increases, restrictions on lease assignment, or termination provisions.
Better Approach: Have a qualified commercial real estate attorney review the lease before closing. Confirm that its duration, renewal rights, rental obligations, and other provisions satisfy the proposed lender’s requirements.
3. Ignoring Building Repairs and Deferred Maintenance
Funeral homes often operate from specialized properties containing preparation rooms, chapels, refrigeration equipment, and other essential facilities.
Unexpected roofing repairs, mechanical system replacements, accessibility improvements, or equipment upgrades can significantly increase the total acquisition cost.
Better Approach: Arrange appropriate property inspections and obtain realistic repair estimates before finalizing the financing plan. Discuss major improvements with the lender to determine whether the project budget and available capital remain sufficient.
4. Underestimating Rent and Property Ownership Expenses
Funeral home buyers sometimes focus on the acquisition price without fully accounting for ongoing property expenses.
Commercial rent, property taxes, insurance, maintenance, and future building improvements can reduce the cash flow available for loan payments.
This is especially important when the seller previously owned the property and charged the operating business below-market rent.
Better Approach: Prepare a realistic post-acquisition budget that includes all property-related costs. Evaluate whether the funeral home’s projected cash flow and debt service coverage ratio (DSCR) can support these obligations.
5. Separating Real Estate From the Business Without Financing Planning
Some buyers create a separate LLC to own the funeral home property while another company operates the business.
Although this arrangement may support certain legal or ownership objectives, it can introduce additional underwriting requirements, intercompany leases, guarantees, and collateral considerations.
Better Approach: Discuss the proposed ownership structure with the lender, attorney, and accountant before establishing separate entities. Confirm that the arrangement meets applicable financing program requirements.
6. Waiting Until Underwriting to Address Property Issues
Delaying property due diligence is another common reason funeral home acquisition loans encounter problems.
Unresolved title concerns, environmental findings, zoning restrictions, low appraisals, or missing property documents may surface late in the financing process.
By that stage, the buyer may have already invested significant time and money in the transaction.
Better Approach: Identify major real estate risks before submitting the full loan application. Gather property documents, review permitted uses, discuss environmental requirements, and coordinate necessary inspections early.
How to Avoid Funeral Home Real Estate Financing Delays
The most effective approach is to evaluate the operating business and commercial property together before making a binding financial commitment.
Funeral home buyers should review the property’s valuation, lease terms, operating expenses, physical condition, legal ownership, and applicable lending requirements.
A complete financial plan should also account for the down payment, closing costs, necessary property improvements, and working capital after acquisition.
The goal is not simply to secure loan approval. It is to structure a funeral home purchase that can support ongoing business operations and sustainable debt repayment.
Identifying real estate financing risks early can help buyers avoid costly surprises and make more informed acquisition decisions.
Funeral Home Real Estate Financing Checklist for US Buyers
Before purchasing a funeral home with commercial real estate in the United States, buyers should review the property, financing requirements, and potential operating expenses. A complete funeral home real estate financing checklist helps identify problems that could affect loan approval, increase acquisition costs, or delay closing.
Whether you are purchasing the building with the operating business or leasing the property, preparing the necessary documentation early can make lender underwriting more efficient.
1. Review the Funeral Home Property and Purchase Structure
-
Confirm the Assets Included: Determine whether the transaction involves the operating funeral home, commercial real estate, equipment, business goodwill, or a combination.
-
Evaluate the Property Purchase Price: Review the proposed property valuation and distinguish real estate value from the operating business’s value.
-
Inspect Building Condition: Identify necessary repairs, deferred maintenance, equipment replacements, and potential renovation expenses.
-
Verify Zoning and Permitted Use: Confirm that the property can legally continue operating as a funeral home following the acquisition.
2. Complete Property Due Diligence
-
Review Environmental Requirements: Ask the lender whether a Phase I Environmental Site Assessment or additional environmental documentation is necessary.
-
Check Property Title and Existing Liens: Confirm ownership records and identify outstanding mortgages, liens, or other title concerns.
-
Evaluate Post-Closing Property Costs: Account for insurance, property taxes, utilities, maintenance, and anticipated improvements.
-
Review Lease Agreements When Applicable: Check lease duration, renewal rights, rent increases, assignment provisions, and maintenance responsibilities.
3. Prepare for Funeral Home Loan Underwriting
-
Confirm Lease Transfer Rights: If leasing, verify that the agreement can be assigned to the buyer and provides sufficient operational stability.
-
Determine Required Equity and Working Capital: Estimate the down payment, closing costs, operating reserves, and funds needed for repairs.
-
Compare Financing Options: Discuss eligible SBA 7(a), SBA 504, and conventional commercial real estate financing structures with the lender.
-
Coordinate Professional Advisors: Consult the lender, qualified commercial real estate attorney, and accountant about property ownership, financing, and tax considerations.
Why This Checklist Matters for Loan Approval
A funeral home may demonstrate strong historical earnings but still encounter financing problems if the property appraisal, lease arrangement, environmental review, or building condition does not satisfy the lender’s requirements.
Completing these checks before making substantial nonrefundable commitments can help buyers develop a realistic acquisition budget and identify issues that may require additional equity, revised loan terms, or further documentation.
The goal is to ensure that the funeral home’s commercial property supports long-term operations, sustainable cash flow, and the proposed financing structure.
Organizing property documents, financial records, and due diligence findings before underwriting can help reduce avoidable delays and improve preparation for closing.
Frequently Asked Questions About Funeral Home Real Estate Financing
1. Does Owning the Funeral Home Building Make It Easier to Get a Loan?
Owning the funeral home building may strengthen a loan application because commercial real estate can provide additional collateral and long-term operational stability. However, property ownership does not automatically guarantee financing approval. US lenders also evaluate the property’s appraised value, business cash flow, debt service coverage ratio (DSCR), buyer qualifications, and available equity. An overpriced building or significant repair costs can create financing challenges even when the funeral home operates profitably.
2. Can I Get a Funeral Home Loan If the Building Is Leased?
Yes, funeral home buyers may qualify for acquisition financing without purchasing the commercial property. Lenders typically review the lease duration, renewal options, rent increases, assignment rights, and the business’s ability to maintain operations at the location. A secure, affordable, long-term lease can support financing, while unfavorable rental terms or limited occupancy rights may increase underwriting concerns.
3. Can SBA 7(a) or SBA 504 Loans Finance Funeral Home Real Estate?
Yes. Eligible SBA 7(a) loans can finance qualifying funeral home acquisitions that include commercial real estate, equipment, business goodwill, and certain working capital needs. SBA 504 financing primarily supports eligible owner-occupied commercial property purchases, construction, improvements, and qualifying major equipment. Unlike SBA 7(a), the 504 program generally cannot finance business goodwill or ordinary working capital. Both programs have specific eligibility, occupancy, and lender requirements.
4. What Happens If a Funeral Home Property Appraisal Is Lower Than the Purchase Price?
When a funeral home property appraises below the proposed purchase price, the lender may reconsider the amount of financing supported by the real estate. The buyer may need to negotiate a lower price, contribute additional equity, review the allocation between property and business assets, or explore another financing structure. A low appraisal does not automatically cause loan denial, but it can affect collateral requirements, available financing, and the closing timeline.
5. Should Funeral Home Real Estate Be Owned Through a Separate LLC?
Holding funeral home real estate in a separate LLC may be appropriate for certain ownership, tax, or long-term property planning objectives. Under this structure, one entity owns the building while another operates the funeral home and pays rent. However, lenders may require additional documentation, intercompany lease agreements, collateral arrangements, or personal guarantees. Buyers should discuss the proposed ownership structure with their lender, qualified attorney, and accountant before establishing separate entities.
Funeral Home Real Estate Financing: Final Thoughts
Funeral home real estate financing is an important part of buying, expanding, or refinancing a funeral home in the United States. Whether you purchase the building with the operating business, lease commercial property, or structure the real estate under a separate entity, your decision can directly affect loan approval, available collateral, business cash flow, and long-term operating stability.
Buying funeral home real estate may provide greater property control, additional collateral, and potential long-term equity. However, property appraisals, maintenance expenses, environmental requirements, and higher acquisition costs must be carefully evaluated.
Leasing a funeral home property may reduce the initial investment, but buyers should review rental expenses, lease duration, renewal rights, and the impact on debt service coverage ratio (DSCR).
When comparing SBA 7(a), SBA 504, and conventional commercial real estate loans, the best financing structure depends on the transaction’s eligibility, property value, business performance, available buyer equity, and repayment capacity.
Before making a final purchase decision, review the property’s condition, legal requirements, financing terms, and post-closing operating expenses. A well-prepared real estate financing strategy can help prevent costly underwriting delays and support sustainable funeral home ownership.
Need Help Structuring Your Funeral Home Real Estate Loan?
At FuneralHomeLoan.com, Matt Manske helps funeral home buyers and owners evaluate financing options for business acquisitions, commercial real estate purchases, expansion, and refinancing.
With more than 20 years of funeral home lending experience, Matt works through established banking relationships to help borrowers understand lender requirements, assess available financing structures, and prepare for the loan process.
Whether you are purchasing a funeral home with its building, leasing property from the seller, or considering real estate refinancing, professional financing guidance can help you evaluate your options before making a commitment.
Call Matt Manske directly at 913-343-2357 to discuss your funeral home financing options.
Direct bank lending guidance. No brokers. No upfront fees. Confidential consultation.
Loan eligibility, financing amounts, collateral requirements, repayment terms, and approvals depend on borrower qualifications, lender underwriting, and applicable loan program rules. This article is for general educational purposes and does not constitute a financing commitment or legal or tax advice.