A funeral home may have a building worth $700,000, vehicles and equipment worth $150,000, and an asking price exceeding $2 million. Where does the additional value come from, and will a bank finance it?
Much of that difference may represent goodwill: the reputation, established business relationships, and ongoing earning power that make a funeral home valuable beyond its physical assets.
However, funeral home goodwill valuation for a bank loan is not simply the amount a seller believes the business is worth. Lenders need evidence that the goodwill has measurable economic value and that the business can generate enough cash flow to repay the proposed financing.
Understanding how banks separate goodwill from hard assets can help buyers avoid overpaying, negotiate more effectively, and prepare stronger financing applications.
What Is Goodwill in a Funeral Home Valuation?
Goodwill is the intangible value associated with an established business that cannot be attributed solely to its identifiable physical assets or other separately valued assets.
For funeral homes, goodwill may reflect years of providing reliable service to families and building a recognizable presence in the community.
Its value can be supported by factors such as:
- Established community reputation and repeat family relationships.
- Consistent funeral call volume and historical operating profitability.
- Experienced employees and established referral relationships.
- Recognizable branding and a defensible local market position.
- Business operations that can continue successfully under new ownership.
Goodwill is not the same as revenue or cash in the bank. A funeral home may generate substantial revenue while producing limited profit, making its goodwill less valuable to a lender than the seller expects.
The key question is whether the business’s earning power will continue after ownership changes.
For a broader explanation of the distinction between tangible and intangible value, read How Lenders Think About Goodwill vs. Hard Assets.
Goodwill vs Hard Assets: What Is the Difference?
Banks evaluate goodwill and hard assets differently because they provide different forms of value and security.
Hard assets are physical items that can generally be appraised, pledged as collateral, and potentially sold. Goodwill depends on the continued success of the operating business.
| Valuation Factor | Hard Assets | Goodwill |
| Examples | Buildings, vehicles, equipment | Reputation, relationships, ongoing earning power |
| Valuation basis | Property appraisals and asset values | Earnings, market evidence, business risk |
| Collateral value | Generally identifiable and recoverable | Limited standalone liquidation value |
| Primary lender concern | Asset condition and recoverability | Sustainable future earnings |
| Effect of ownership change | Physical assets generally remain | Value may decline if relationships or operations deteriorate |
A bank may be comfortable valuing a funeral home’s real estate while questioning whether the same business can maintain its customers, service standards, and profitability after the seller retires.
That distinction becomes especially important in acquisitions where goodwill represents a large share of the purchase price.
How Do Banks Calculate Funeral Home Goodwill?
Banks typically evaluate the operating business, its identifiable assets, and its intangible value as related but separate components.
1. Determine the Value of the Operating Business
Lenders often begin with a business valuation supported by historical earnings, normalized cash flow, and comparable transactions.
A common approach uses adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA).
Illustrative operating business value = Adjusted EBITDA × Supported Valuation Multiple
Suppose a funeral home generates $300,000 in normalized annual EBITDA, and market evidence supports a 5× EBITDA multiple.
The indicated operating business value would be:
$300,000 × 5 = $1,500,000
This is an illustrative valuation, not a guaranteed sale price or bank-approved amount.
The actual multiple depends on business size, financial performance, market conditions, owner dependency, and other risk factors.
For more detail about this calculation, see How Funeral Home Valuations Are Calculated: EBITDA Multiples Explained.
2. Identify and Value Hard Assets
The next step is determining which tangible assets are included in the transaction.
These may include furniture, preparation equipment, hearses, service vehicles, cremation equipment, and other business property.
Real estate is generally valued separately when included in the purchase.
Banks may rely on independent appraisals rather than the seller’s estimated replacement cost or original purchase price.
3. Calculate the Supported Intangible Value
Goodwill is commonly determined as a residual after allocating the supported purchase value to identifiable net assets and any other separately recognized intangible assets.
Consider this simplified example:
| Valuation Component | Amount |
| Operating business value | $1,500,000 |
| Identifiable net operating assets included | $350,000 |
| Residual goodwill and other unallocated intangible value | $1,150,000 |
| Separately appraised real estate | $800,000 |
| Total indicated transaction value | $2,300,000 |
This example assumes no separately valued intangible assets, additional liabilities, or adjustments to the agreed working capital.
It also assumes the operating business value already includes the $350,000 of net operating assets. Those assets should not be added again.
Important: A residual calculation is not, by itself, an independent bank valuation. The final goodwill allocation must reflect the actual assets, liabilities, accounting treatment, and valuation methodology applicable to the transaction.
What Factors Increase or Reduce Funeral Home Goodwill Value?
A funeral home’s reputation may attract buyers, but lenders focus on whether the underlying business performance is transferable and sustainable.
Consistent Funeral Call Volume
A funeral home with stable or growing calls provides stronger evidence of continuing local demand.
Banks typically examine multiple years of call history rather than relying on a single strong year.
A sudden decline can raise concerns about competition, demographic changes, management problems, or lost customer relationships.
Revenue and Profitability Per Call
Higher call volume does not automatically mean stronger goodwill.
Banks also consider average revenue per service, burial and cremation mix, merchandise revenue, direct costs, staffing, and operating margins.
For example, a funeral home completing 300 calls annually may produce less operating profit than one completing 220 calls if its overhead is substantially higher.
Preneed Contracts and Future Obligations
A well-managed preneed program can provide useful information about future service demand. However, lenders must distinguish potential future revenue from funded assets, trust arrangements, insurance assignments, and contractual obligations.
Preneed balances should not automatically be treated as unrestricted cash or added dollar-for-dollar to goodwill. The buyer must understand applicable state regulations and any obligations transferred with the business.
Owner Dependency and Management Continuity
Goodwill becomes less secure when most customer relationships depend on a retiring owner. A bank may question whether families will continue choosing the funeral home after that individual leaves.
Retaining experienced funeral directors, maintaining service quality, and establishing a realistic transition plan can help address this risk.
How Does Goodwill Affect Bank Loan Approval?
A funeral home’s valuation and its financing capacity are connected, but they are not identical. Even when an independent valuation supports the purchase price, the buyer must demonstrate the ability to repay the requested loan.
Cash Flow and Debt Service Coverage
Banks commonly evaluate the debt service coverage ratio (DSCR), which compares available cash flow with required debt payments.
DSCR = Cash Flow Available for Debt Service ÷ Annual Debt Service
Consider a funeral home with the following financial position:
| Metric | Amount |
| Annual cash flow available for debt service | $240,000 |
| Proposed annual debt payments | $180,000 |
| DSCR | 1.33× |
A DSCR of 1.33× means the business has approximately $1.33 in available cash flow for each $1 of annual debt service.
Now suppose normalized available cash flow is only $200,000.
The ratio falls to approximately 1.11×, which may be insufficient for the proposed loan structure.
For SBA 7(a) change-of-ownership transactions, current requirements generally call for at least 1.25× historical pro forma debt service coverage, with a specific lower threshold for qualifying business expansions.
A strong valuation does not replace the need to satisfy applicable repayment requirements.
Collateral and Buyer Equity
Because goodwill provides limited liquidation protection, banks may evaluate high-goodwill transactions more cautiously.
Lenders may consider borrower equity, available collateral, management experience, seller financing, and transaction structure.
Goodwill does not automatically make an acquisition ineligible for financing.
For buyers considering a business purchase involving substantial intangible value, Funeral Home Acquisition Loans explains how acquisition financing can address real estate, equipment, and goodwill within the transaction.
Can an SBA Loan Finance Funeral Home Goodwill?
Yes. SBA 7(a) financing can support qualifying business acquisitions that include goodwill and other intangible assets.
This is particularly relevant for funeral homes because substantial business value may exist beyond real estate and equipment.
Under SBA SOP 50 10 8.1, effective October 1, 2026, change-of-ownership financing includes specific requirements for business valuations, financial due diligence, equity, and repayment capacity.
An independent third-party business valuation is required for change-of-ownership transactions. The valuation must be requested by and prepared for the lender and include an allocation of goodwill.
If the agreed purchase price exceeds the supported valuation, the buyer may need additional equity to cover the difference.
The SBA 504 program, by contrast, focuses on eligible fixed assets and generally cannot finance business goodwill as an eligible project cost.
Buyers should review SBA 7(a) Funeral Home Loans to understand how this financing option may apply to acquisitions involving intangible assets.
What Happens if the Bank Values Goodwill Below the Asking Price?
A low goodwill valuation can create a financing gap.
Suppose a seller asks $2.4 million for a funeral home acquisition, but the independent valuation supports only $2.1 million.
The $300,000 difference does not automatically become eligible for additional borrowing simply because the buyer and seller agree on the higher price.
Potential responses include renegotiating the purchase price, increasing the buyer’s equity contribution, or restructuring eligible financing subject to lender approval. Before choosing a solution, the buyer should understand why the valuation came in lower.
Common causes include unsupported earnings adjustments, declining call volume, owner dependency, aging equipment, or an asking price based on optimistic future projections. A lower valuation may be a useful warning about acquisition risk rather than merely an obstacle to approval.
How Can Buyers Prepare for a Bank Goodwill Valuation?
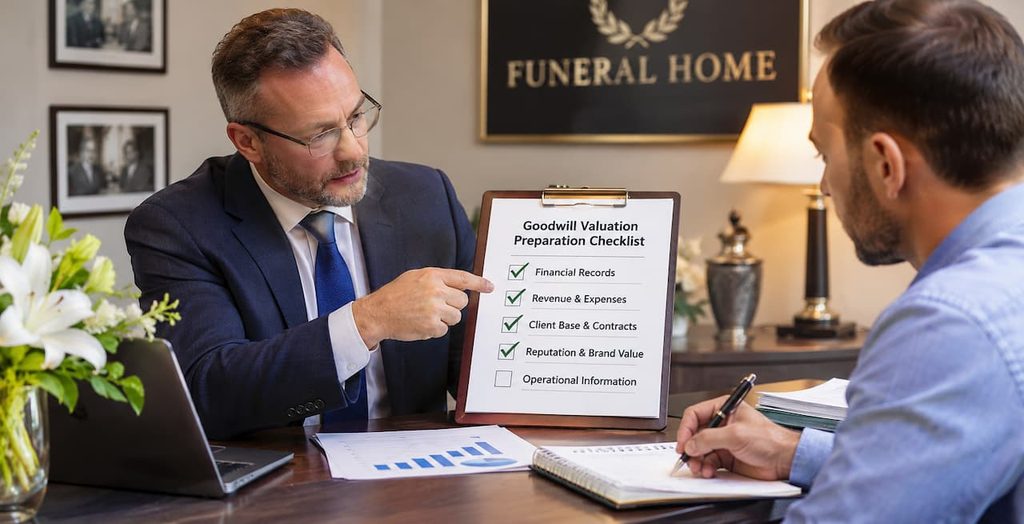
The most effective approach is to verify the business’s earnings and operational stability before finalizing the acquisition structure.
Documents Banks Commonly Review
Prepare the following information early:
- Three years of business tax returns, financial statements, and call volume records.
- Current year-to-date and trailing 12-month financial statements.
- A detailed list of proposed earnings add-backs and supporting documentation.
- An equipment inventory, real estate details, and relevant existing debt information.
- Preneed reports, applicable obligations, and a written ownership transition plan.
Buyers should also confirm that the purchase agreement clearly identifies the included assets, liabilities, and real estate.
Reviewing the Funeral Home Acquisition Checklist: What Banks Want to See can help organize the required information before formal underwriting.
Verify the Earnings Adjustments
Sellers may propose adjustments for personal expenses, excessive owner compensation, or one-time costs.
Banks do not necessarily accept every adjustment.
Each proposed add-back should be documented, and the analysis should account for any replacement salary or expense the buyer will incur after closing.
Unsupported adjustments can artificially increase EBITDA and goodwill value.
Stress-Test Future Performance
Buyers should calculate whether the funeral home can service acquisition debt if call volume, revenue per call, or operating margins decline.
A business with strong historical goodwill may still struggle with its financing if new debt payments leave little room for unexpected expenses.
A conservative cash flow forecast is more useful than assuming the business will immediately grow after acquisition.
Does Conventional Financing Treat Goodwill Differently?
Often, yes.
Conventional commercial lenders generally place considerable importance on collateral, borrower financial strength, and sustainable business cash flow.
Some lenders may consider a substantial goodwill component, while others prefer transactions supported primarily by real estate and identifiable physical assets. There is no universal rule that all conventional lenders will finance a fixed percentage of goodwill.
A business with strong real estate collateral, established operations, and experienced ownership may have more conventional financing options than an acquisition consisting almost entirely of intangible value.
Explore Commercial Funeral Home Loans for details about conventional financing structures.
Existing owners considering debt restructuring or acquisition-related refinancing can also review Refinancing for Funeral Homes to understand how banks evaluate repayment capacity and collateral in refinancing transactions.
Frequently Asked Questions
How do banks value funeral home goodwill?
Banks evaluate goodwill through an independent business valuation, supported earnings, market evidence, and the allocation of value between identifiable assets and intangible value. They also assess whether the business can maintain its earnings under new ownership.
Is funeral home goodwill considered collateral?
Goodwill may form part of the acquired business assets and loan security package, but it generally has limited standalone liquidation value. Lenders primarily depend on sustainable cash flow to support repayment of goodwill-related financing.
Can a bank finance goodwill without funeral home real estate?
Yes, depending on the financing program, borrower qualifications, business performance, and lender requirements. SBA 7(a) financing may be available for qualifying business-only acquisitions even when real estate is not purchased.
How much goodwill is too much in a funeral home purchase?
There is no universal acceptable percentage. A large goodwill allocation becomes problematic when the valuation cannot support it, earnings are unstable, or the proposed debt cannot be serviced.
Does a funeral home’s reputation increase its bank valuation?
A strong reputation can support goodwill when it produces measurable business performance. Banks need evidence through call volume, profitability, operating history, and ongoing customer demand rather than reputation claims alone.
Do preneed contracts count toward goodwill?
Preneed business may support future revenue expectations and valuation, but its treatment depends on funding arrangements, contractual obligations, transferability, and applicable regulations. It should not automatically be added to goodwill at face value.
What if the bank’s goodwill valuation is lower than the seller’s price?
The buyer may need to renegotiate the price, contribute additional equity, or revise the transaction structure. The lender’s supported valuation and applicable program requirements will affect the financing available.
Does the seller’s retirement affect goodwill value?
It can. If the business depends heavily on the seller’s personal relationships, banks may be concerned about customer retention and management continuity. A detailed transition plan can help address those concerns.
Get Bank-Level Guidance Before Buying a Funeral Home
Goodwill can represent a substantial portion of a funeral home’s value, but an asking price alone does not establish what a bank can finance.
Buyers need a supported business valuation, reliable cash flow, a realistic transition plan, and a financing structure that fits the combination of goodwill and hard assets.
FuneralHomeLoan.com specializes in funeral home acquisition, SBA, and conventional commercial financing. Matt Manske brings more than 20 years of industry-specific lending experience and works directly through federally insured banks.
If you are evaluating a funeral home purchase involving significant goodwill, discuss the transaction before committing to a financing structure.
Call Matt Manske at (913) 343-2357 or request a confidential financing conversation.